Expense IQ Money Manager
Handy AppsFinanceVerified
- 2.81K Reviews
- 3.2
- Downloads
- 1,000,000+
- Price
- Free
Screenshots
 Analysis by Appwesome
I judge money-management apps less by how polished they look and more by how clearly they let me understand and control my financial information. Expense IQ Money Manager, developed by Handy Apps, takes a practical approach: it brings spending records, budgets, and bill reminders into one finance app instead of making me jump between separate tools. I found that useful for everyday organization, but I also think this is the kind of app that deserves a careful look before you enter sensitive financial details.
It is free to install, rated for Everyone, and available for devices running Android 4.4 or later. The app has been around since May 14, 2014, and its current version is 2.3.2. Its long presence and broad adoption give it a familiar feel, although popularity alone is not proof that it is the right choice for your privacy expectations or personal workflow.
Handy Apps presents Expense IQ as an all-in-one money manager. In practical terms, I see it as a manual financial notebook with planning tools attached: you record transactions, organize spending, set limits, and use reminders to keep recurring obligations visible. That distinction matters. If you want automatic banking connections or a completely hands-off experience, this may not suit you. If you prefer deciding exactly what gets recorded, it can be more comfortable.
How Expense IQ handles trust, control, and daily money tracking
A familiar finance tool with a realistic trust question
The app has an average rating of 3.2 from around 23 thousand ratings, with roughly 2.8 thousand written reviews and over 1 million installs. I would read those figures as evidence of meaningful use rather than a guarantee of quality. A finance app can be popular while still frustrating some people with its interface, workflow, or limits, so I would not treat the install count as a substitute for checking whether its controls match your needs.
My first impression is that Expense IQ is aimed at people who want visibility rather than investment management. It is useful for answering ordinary questions: Where did my money go this week? Am I close to my food budget? Which bills need attention? The strength is its focus on those repeated decisions. The weakness is that the value depends on consistent input and on your comfort with the way the app stores and handles what you enter.
That makes trust a practical issue, not an abstract one. Before recording account balances, income, debts, or detailed spending habits, I would inspect the app’s permission prompts, privacy information, and any account or backup settings shown on the device. I would also avoid assuming that a finance app is automatically connected to a bank, encrypted in a particular way, or independent of external services unless the app clearly explains those points.
Expense IQ is not the same as a banking app. That can be reassuring because you are not necessarily handing it the same role as your bank, but it also means you should not expect bank-level transaction synchronization simply because the app is in the Finance category. The safest workflow is to treat every entry as information you are intentionally placing into a separate budgeting record.
Other Stories to Read




Manual recording is both the main strength and the main burden
For me, the most important choice is whether I am willing to record purchases regularly. A manual tracker gives me more control over what appears in the ledger. I can decide how to describe a cash purchase, how to split a shared expense, and whether a transaction belongs to a personal or household budget. That level of choice is often missing from overly automated alternatives.
The trade-off is obvious after a busy day. If I buy coffee, take public transport, pick up groceries, and pay for a subscription without entering anything, the app cannot reconstruct my behavior by itself. A good routine is to record purchases at the moment they happen or reserve a short daily check-in. Waiting until the end of the month makes small expenses harder to remember and weakens the budget picture.
One useful tactic is to begin with only the categories that affect decisions. Instead of creating a long list immediately, I would start with housing, food, transport, bills, leisure, and irregular spending. After a week or two, I would add categories only when the extra detail changes what I do. This keeps entry quick and prevents the app from becoming a bookkeeping project.
Another practical habit is to write notes for unusual transactions rather than forcing every purchase into a misleading category. A medical payment, annual renewal, or reimbursable work expense may need context later. The benefit is not decorative detail; it is being able to understand why a month looks different when you review it.
Budgets work best when they answer a specific question
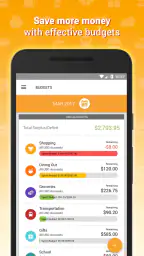
The budget planner is more useful when I treat it as a decision tool rather than a scorecard. A broad monthly limit can tell me that spending is high, but a focused limit can explain what needs attention. For example, separating groceries from restaurant meals makes it easier to see whether the problem is food cost in general or convenience spending in particular.
I would also avoid setting targets so aggressively that they become unrealistic after one unexpected expense. A budget should help me choose what to do next, not make every ordinary variation feel like failure. In Expense IQ, the most useful review would be the conversation between planned spending and actual spending: which category repeatedly runs over, which one is consistently overestimated, and which costs should be treated as periodic rather than monthly?
A less obvious advantage of manual planning is that it can expose irregular expenses that automatic tools often blur into a general account balance. If a yearly payment is recorded only when it arrives, it can look like a sudden problem. I would use the planning process to set aside a small amount for those predictable but infrequent costs. That turns the app from a history log into a preparation tool.
Bill reminders are helpful, but they are not payment protection
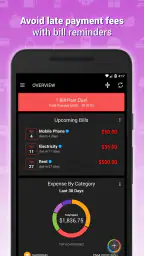
The bill reminder feature addresses a different problem from budgeting. A budget tells me whether I can afford an obligation; a reminder helps me remember that it is due. I would use the two together, especially for utilities, subscriptions, insurance, and other recurring charges that are easy to overlook.
However, I would not treat a reminder as proof that a payment was completed. After paying a bill, I would record the transaction and check it against the reminder. This two-step habit matters because a notification can be dismissed, missed, or misunderstood. The app can keep an obligation visible, but I remain responsible for confirming the payment through the relevant provider or account.
There is also a useful privacy angle here. A reminder can be labeled in a way that is meaningful to me without including unnecessary sensitive details. I would use a simple description and avoid putting full account numbers, login information, or other credentials into notes. A money manager should contain enough information to organize finances, not become a storage place for secrets that do not belong there.
What I would check before trusting it with sensitive information
Because this is a finance app, I would review the visible choices during setup and whenever the app asks for access. I would pay attention to whether a permission is necessary for the task I want to perform, whether it can be declined, and whether the app still works for basic manual tracking without granting optional access. I would not grant a permission simply because the request appears during onboarding.
I would also look for account controls, sign-in options, backup choices, and deletion controls inside the app or its accompanying policy pages. These details affect how easily I can leave, move to another tool, or protect the information if my phone is lost. If an account is optional, I would consider starting with the least revealing setup and adding services only when I understand their purpose.
This cautious approach does not mean I assume the app is unsafe. It means I separate what I can observe from what I am merely hoping is true. The visible permission dialogue, the settings available to me, and the explanations attached to data practices are more useful than vague assumptions about any finance application.
I would be especially careful with synchronization or backup choices. Convenience can be valuable, but a copy of a financial record in another place creates another point that I need to understand. Before enabling anything that moves data away from the device, I would check what is being synced, which account controls it, how I can turn it off, and whether removing the app also removes stored information.
A realistic household workflow
Imagine I am managing a monthly household budget with a partner. At the start of the month, I would enter expected income and establish only the spending limits that matter most. I would add recurring bills to the reminder area, then record purchases as they happen. For shared expenses, I would use a clear note such as “household reimbursement” rather than relying on memory later.
At the end of each week, I would compare the recorded categories with actual receipts and account activity. This is where manual tracking earns its keep: a forgotten cash purchase becomes visible, a subscription that no longer feels worthwhile stands out, and a category that was set too low can be adjusted before it causes unnecessary stress. I would not wait until the month ends, because late corrections reduce the value of the budget.
For a couple, the app may work best when both people agree on a simple recording convention. If one person calls a purchase “food” and the other calls a similar purchase “dining,” the reports become less useful. The app cannot solve disagreements about categories, so the household needs a shared method. That is a small but important limitation of any manual system.
Where it compares well, and where another option wins
Compared with a paper notebook, Expense IQ offers a more structured way to connect transactions, spending limits, and reminders. Compared with a basic notes app, it is designed around financial records rather than free-form text. Those are meaningful advantages if I want my entries to support review instead of simply preserving a list.
Compared with bank-connected budgeting services, the manual approach may feel slower. Automatic imports can reduce the effort of capturing transactions and may be better for someone with many accounts or a high volume of card purchases. The downside is that imported data can require cleanup, category corrections, and trust in the connection. Expense IQ’s appeal is strongest for someone who would rather enter fewer details deliberately than authorize a broader connection.
Compared with a spreadsheet, the app is more convenient for quick entries and recurring personal use, while a spreadsheet offers greater flexibility for custom formulas, shared analysis, and long-term exports. I would choose a spreadsheet if I needed detailed forecasting or a business-style ledger. I would choose Expense IQ if I wanted a phone-centered routine without building the structure myself.
The free price makes it easy to try without an upfront purchase, but in-app purchases range from about three dollars and fifty cents to around one hundred twenty-five dollars per item. I would check exactly what a paid option unlocks before buying, especially if I only need basic expense recording. A free starting point is useful, but it does not automatically mean every advanced function is included.
Small habits that reveal the app’s real value
The first habit I recommend is a “capture now, classify later” routine for hectic moments. I would record the amount and a short description immediately, then choose the final category during the evening review. This avoids losing purchases while also preventing me from stopping in the middle of a queue to make a perfect classification.
The second is to separate predictable bills from flexible spending. If both are mixed together, a large rent or insurance payment can make the month look worse than it really is. Keeping the review focused on controllable categories gives me a clearer answer to the question, “What can I change next week?”
The third is to use a monthly reset that checks not only totals but also the quality of the records. I would look for duplicate entries, forgotten cash spending, vague descriptions, and reminders that no longer apply. This is especially important in a manual app because inaccurate input can create convincing but false conclusions.
A fourth insight is to keep the app’s role narrow. I would not use it as a password vault, document archive, or place for full payment credentials. A focused record of amounts, dates, categories, and useful notes is easier to maintain and limits the damage if the information is ever exposed or simply becomes difficult to manage.
Who should use it and who should look elsewhere
I think Expense IQ is a good fit for someone who wants a personal spending log, simple budget planning, and bill reminders in one Android app. It suits people who prefer manual control, want to understand their habits, and are willing to build a regular recording routine. It can also help someone moving away from paper without needing the complexity of a full financial dashboard.
I would be more hesitant to recommend it to someone who expects automatic bank feeds, advanced investment tracking, collaborative household controls, or a sophisticated business accounting system. Those users may be better served by a specialized service or spreadsheet that matches the job more directly. I would also skip it if I know I will not enter transactions consistently; an unused tracker is not more helpful than a notebook left in a drawer.
Privacy-conscious users should make their decision after reviewing the app’s current permission prompts, account settings, backup choices, and data explanations on their own device. The important question is not whether the app looks trustworthy at first glance, but whether its visible controls let me make an informed choice about what I record and where it goes.
My cautious verdict
After looking at Expense IQ as a daily finance tool rather than a feature checklist, I see a sensible middle ground. It is more organized than a notes page, less demanding than a custom spreadsheet, and more deliberate than an automatically connected budgeting service. Its strongest quality is the way manual entry can make spending feel concrete. Its biggest weakness is that the same manual process requires discipline and can become tedious.
I would install it for a short trial using ordinary categories and limited personal detail. I would test a few expenses, one budget, and a reminder before deciding whether the workflow feels natural. During that trial, I would inspect permissions and account controls rather than rushing through setup. If the app helps me review money calmly and gives me enough visible choice over my information, it is worth keeping.
My recommendation is therefore measured: Expense IQ Money Manager is worth considering for straightforward, hands-on expense tracking, but I would not choose it blindly for complex finances or automatic account management. The free entry point lowers the barrier to testing it, while the paid options make it important to understand what I actually need. The right reason to use it is control through a consistent routine, not the promise of effortless financial management.
Highlights
- Clear expense categories make spending patterns easy to understand.
- Recurring transactions reduce the effort needed for regular bills.
- Budget alerts help you notice overspending before it becomes a problem.
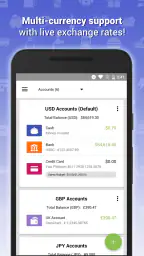
- Multiple account support keeps cash
- bank
- and card balances organized.
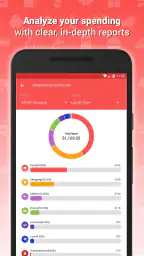
- Detailed reports provide useful insight into long-term financial habits.
Limitations
- Some advanced features may require a paid upgrade.
- Manual entry can feel time-consuming for frequent transactions.
- Bank synchronization may vary by country or financial institution.
- The interface can feel dated compared with newer finance apps.
- Users may need to customize categories for more specialized budgets.
Frequently Asked Questions
01What is Expense IQ Money Manager used for?
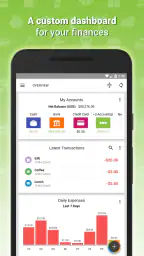
Expense IQ Money Manager is a personal finance app designed to help you track spending, organize income and expenses, manage budgets, and monitor your overall financial habits. After setting up accounts and categories, you can record transactions, review summaries, and use charts or reports to understand where your money goes. It is useful for everyday budgeting, household finances, and keeping several accounts organized in one place.
02Can I use Expense IQ Money Manager to manage multiple accounts and budgets?
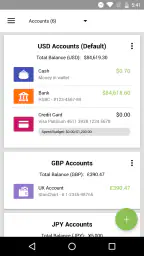
Yes, the app is intended for users who need to manage more than one financial account, such as cash, bank accounts, credit cards, or savings. You can separate transactions between accounts and create spending categories or budget limits for different areas of your life. This makes it easier to compare planned spending with actual expenses, although the quality of the results depends on entering transactions accurately and consistently.
03Does Expense IQ Money Manager connect directly to my bank?
Expense IQ Money Manager is primarily focused on manual personal-finance tracking rather than requiring automatic bank access. Depending on the version and platform, available import, synchronization, or backup options may vary, so users should check the current app listing before downloading. Manual entry gives you more control and privacy, but it also means you must regularly record purchases, deposits, transfers, and other financial activity yourself.
04Is my financial information safe when using Expense IQ Money Manager?
Because the app can contain sensitive information about your spending, accounts, and financial routines, you should review its current privacy policy and permissions before adding real data. Use any available passcode or security-lock feature, keep your device protected, and avoid sharing exported files carelessly. Backup and synchronization settings should also be checked, since storing data online or on another device may involve additional privacy considerations.
05Is Expense IQ Money Manager free to download, and are there premium features?
Expense IQ Money Manager may be available as a free download with optional paid features, depending on the operating system, region, and current version. Premium tools can potentially include expanded reports, additional customization, backup or synchronization options, or removal of advertising. Before installing, review the store page for the latest pricing, subscription details, trial terms, and limitations so you know which features are included without payment.


